Principal®

Screenshots
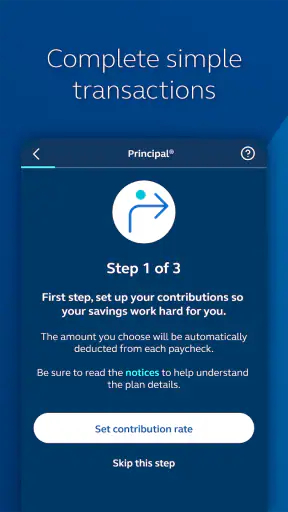
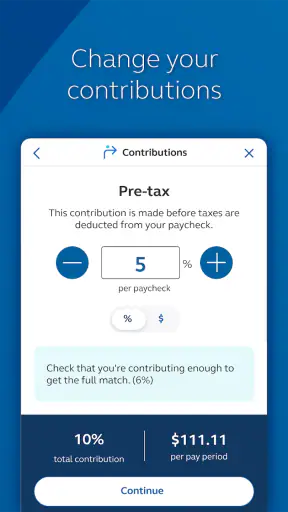
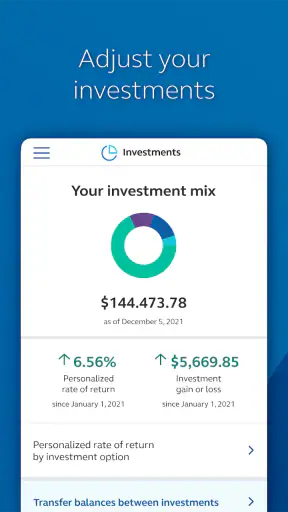
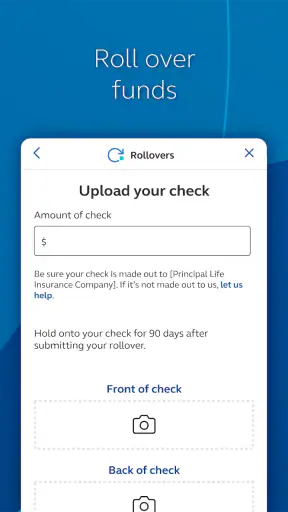
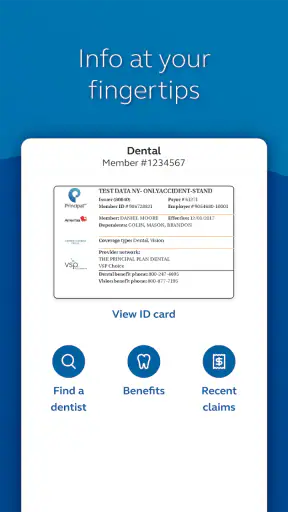
Details
- Rating
- 2.32K reviews
- Version
- 4.0.146
- Developer
- Principal Financial Group, Inc.
Analysis by Norviv
Managing money from a phone sounds useful only if the app becomes part of your normal routine rather than another icon you forget after a week. I spent time with Principal® with that question in mind: does it genuinely help me keep track of financial goals on the go, or does the convenience wear off quickly? My impression is that it is most valuable for people who already use Principal for their financial arrangements and want a practical mobile window into them, not for someone looking for a complete replacement for a bank, budgeting suite, or investment research platform.
It is a free finance app from Principal Financial Group, Inc., available for everyone and supported on both Android and iOS. The app has reached over a million installs and holds a 4.7 average from around forty-four thousand ratings, which suggests that many users find its basic purpose dependable. I would not treat those figures as a guarantee that every account experience will feel identical, though. A financial app is only as useful as the information and actions available for a particular user’s Principal relationship.
What the first week feels like
The first-week appeal comes from reducing the distance between a financial goal and the information needed to act on it. Instead of waiting until I am at a computer, I can open the app when I have a spare moment and check where things stand. That matters when a goal is easy to ignore because it feels abstract. A quick mobile check can turn “I should look at that sometime” into a small, repeatable habit.
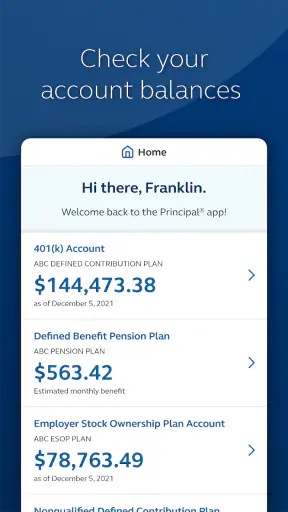
The experience makes the most sense when I approach it as a focused account companion. Principal is not presented as a general-purpose spending tracker where I manually enter every coffee, bill, and subscription. Its identity is tied to financial goals and Principal-held information. That focus is a strength for existing customers because the app does not need to compete with a broad budgeting dashboard to be useful.
During the first few sessions, I would use it to establish a simple routine: open it at a calm time, review the current picture, and decide whether anything actually needs attention. That last step is important. A finance app can create unnecessary anxiety if every visit becomes a demand to make a decision. The better use of this one is as a short check-in, especially when I want awareness without opening a laptop.
The app was released on March 1, 2019, and the current version is 4.0.146. Those details are less important than how the app fits into a current phone routine, but they do show that this is an established product rather than a brand-new experiment. Principal has had time to refine its mobile presence, while the version number also reminds me that app behavior can change after updates. I would keep automatic updates enabled, particularly for a finance app.
One practical advantage is psychological rather than technical: mobile access lowers the effort needed to look at long-term money. If I am already holding my phone, checking a goal can take less commitment than opening a browser and navigating through a desktop account. That small reduction in friction is exactly what makes a financial habit stick. It will not create discipline by itself, but it can support discipline that already has a clear purpose.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
A realistic everyday use case
Imagine receiving income at the end of a workweek and wondering whether a planned contribution or financial target is still on track. I would open Principal, review the relevant information, and use that moment to decide whether I need to follow up or simply leave things alone. Later, before making a larger discretionary purchase, I might check again to keep the decision connected to the bigger goal. The value is not in staring at the screen; it is in bringing a long-term consideration into an ordinary decision.
That workflow is especially useful for someone who tends to postpone financial reviews. It is also useful for a person who travels or moves between home and work and does not want access tied to one computer. On the other hand, a user who expects detailed household budgeting, automatic categorization of spending, or a complete view of accounts held across many institutions may feel that the app is too narrow.
I would also set expectations carefully around the word “on the go.” Convenience does not mean every financial task becomes effortless. Some actions may still require careful reading, extra verification, or a larger screen, depending on the account and what I am trying to do. For quick awareness, the phone is a good fit. For complicated planning, I would rather slow down and use a fuller account environment when available.
Who gets the strongest first impression
The best early experience is likely for an existing Principal customer who wants a mobile way to stay connected to financial goals. That person already understands why the account matters, so the app’s focused nature feels intentional rather than incomplete. Someone beginning with a clear retirement or savings-related objective may also appreciate having a dedicated place to check progress.
The weaker first impression belongs to people who want to bring every part of their financial life into one screen. If my main need is comparing several banks, tracking daily expenses, planning debt payments, or building a detailed monthly budget, I would choose a broader finance tool. Principal can sit beside that kind of app, but I would not expect it to replace it.
What remains useful after the novelty fades
The real test is not whether I enjoy opening a new finance app during the first week. It is whether the app continues to earn a place in my routine once the initial curiosity disappears. Principal’s recurring value comes from making financial awareness easier to maintain. Long-term goals benefit from occasional attention, and a mobile account view can serve as a reminder without requiring a full planning session every time.
My preferred month-to-month pattern would be brief and deliberate. I would choose a regular day, review the account information, note anything that looks different from what I expected, and then close the app. This avoids two common mistakes: never checking at all, or checking so often that normal movement becomes distracting. The app is more useful as a scheduled checkpoint than as a source of constant reassurance.
A second useful pattern is connecting the app to life events. A change in employment, a new recurring expense, a move, or a shift in priorities can justify a closer review. In those moments, mobile access helps me begin the conversation with my finances immediately. It does not eliminate the need for thoughtful planning, but it reduces the delay between noticing a change and looking at the relevant information.
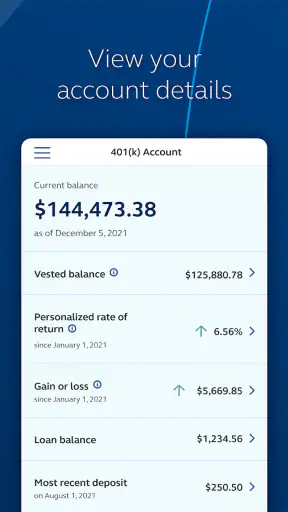
The app’s long-term usefulness also depends on whether I understand what I am seeing. A balance or progress view is only helpful when I know which goal it represents and what kind of change is normal. I would avoid making a major decision based on one glance. Instead, I would use the app to identify questions, then read the account details carefully or seek appropriate guidance when the decision has serious consequences.
This is where Principal differs from the usual general finance alternatives. A broad budgeting app is usually strongest at showing spending behavior across categories and institutions. A bank app is strongest for everyday transactions and cash management. Principal’s role is more specialized: it keeps the user connected to Principal-related financial goals. That specialization can make the experience calmer and more relevant, but it also means the app is not the best single dashboard for someone whose finances are spread across many providers.
I would keep a separate system for expenses if I needed detailed spending control. For example, I might use a budgeting tool to watch grocery costs and recurring bills, while using Principal for the longer-range account relationship. That division is not a weakness by itself. In fact, forcing one app to handle every financial task often creates clutter. The trade-off is that I must remember which app answers which question.
The maintenance burden is small, but not zero
Principal does not remove the need for financial maintenance. I still need to protect access to the account, keep my sign-in details secure, pay attention to notices, and review information with enough care to catch something unexpected. A finance app can make checking easier, but it cannot decide whether a goal still matches my life.
The simplest maintenance habit is to avoid opening the app only when I am worried. A neutral, recurring review makes unusual information easier to spot because I have a sense of what normally appears. I would also avoid logging in casually on shared or public devices and would treat every authentication prompt as something to read rather than dismiss automatically.
Another overlooked task is keeping the app current. The version listed for Principal is 4.0.146, and updates can affect navigation, security, and compatibility. I would not assume that a familiar screen will remain unchanged forever. After an update, I would take a moment to confirm that I can still find the information I use most often instead of discovering a change during an urgent check.
The maintenance burden becomes heavier when I expect the app to answer questions it was not designed to answer. If I want a complete net-worth picture, I may need another tool or a manual review. If I want a detailed contribution strategy, I may need to understand the underlying account and options rather than relying on a headline view. The app can support a process, but it should not become the entire process by default.
Where fatigue can set in
The main source of fatigue is repetition without a clear decision. If I open a finance app every day and see information that has not meaningfully changed, the habit can become empty. That is why I would use it at a sensible interval rather than treating frequent checking as progress. The app earns its place when it helps me notice, understand, or act—not when it simply occupies attention.
A second source of friction is the gap between mobile simplicity and financial complexity. A clean overview is convenient, but important choices often involve details that are not comfortable to evaluate on a small screen. I would be cautious about making a complicated change while distracted, commuting, or rushing. The phone is excellent for awareness; it is not automatically the best setting for every financial decision.
There is also a natural limitation for households with complicated finances. If two people need a shared, complete view of spending, debts, savings, and accounts from different providers, a dedicated household budgeting system may be more practical. Principal can still be useful for the Principal portion of that picture, but it may add one more place to check rather than simplifying everything.
Users who dislike long-term financial tracking may also lose interest. The app cannot manufacture a goal that feels meaningful. If I do not know what I am working toward, a mobile view may feel like a series of numbers without context. I would first define the question I want the app to help me answer: am I checking progress, confirming that information is current, or deciding whether I need a deeper review?
Privacy and trust deserve the same attention as convenience. This is a finance app, so I would judge it by whether I feel comfortable using it for sensitive account access, not merely by how quickly it opens. I would use a secure phone lock, avoid sharing access, and be deliberate with notifications. Those are user habits rather than special features, but they determine whether mobile convenience feels responsible.
Answers I would want before installing
Would I recommend it to someone who does not already use Principal? Only with a qualification. The app is most compelling when it connects to an existing Principal relationship. If a person wants a general budgeting app, a bank app, or an all-in-one financial dashboard, I would point them toward a tool built around that specific need instead.
Is it worth paying for? The app itself is free, so the decision is not about adding a subscription to the monthly budget. The more important question is whether the user has a reason to use Principal’s financial services and wants mobile access to that relationship. Free access is helpful, but it does not make an unsuitable workflow suitable.
Can it replace a financial adviser or a detailed plan? I would not treat it that way. A mobile app can make information easier to review, yet it cannot understand every personal obligation, tax consideration, time horizon, or risk preference. I would use Principal as an access and monitoring tool, then handle complex decisions with the level of research or professional help they deserve.
Is it suitable for younger users? Its content rating is Everyone, which makes it broadly accessible from an age-rating perspective. Still, suitability depends on the person’s actual financial relationship and goals. A teenager looking for a spending tracker may find a simpler educational or budgeting tool more relevant, while an adult managing a Principal account may find the focused access more useful.
What should I do if I want more detail? I would begin with the app’s overview, identify the exact question that remains unanswered, and then move to a fuller account review rather than guessing from a summary. That approach prevents a common mistake in mobile finance: confusing a convenient snapshot with a complete explanation.
My long-term verdict
After the novelty fades, Principal® earns lasting space when it supports a modest, repeatable habit: checking Principal-related financial goals at sensible moments and using that information to stay engaged. Its strongest quality is focus. It does not need to become my entire financial life to be useful, and I would rather have a focused companion that I understand than an overcrowded dashboard I rarely trust.
The app’s limitations are equally clear. It is not the choice I would make for detailed daily budgeting, a multi-institution household overview, or complex financial planning on a phone. Those jobs belong to broader tools or more deliberate review. Principal works best beside those resources, not necessarily instead of them.
For an existing Principal customer, the free mobile access and established presence make it easy to justify trying. The strong average rating and large user base add confidence that the basic experience is working for many people, while the Everyone rating keeps access broad. My recommendation is to install it only after deciding what recurring question it should answer. If that question is “how do I stay connected to my Principal financial goals while away from my computer?”, it has a clear reason to remain on the phone.
My final judgment is favorable but specific: this is a practical finance companion, not a universal money manager. I would keep it if it helped me maintain a regular review without creating extra noise. If, after a few monthly check-ins, I still needed another app for every meaningful decision, I would keep Principal for account access but stop expecting it to organize the whole picture. That is the honest measure of its long-term value: not how impressive it feels on day one, but whether it makes responsible financial attention easier to repeat.
Frequently Asked Questions
01What is Principal® and what can I use it for?
Principal® is a personal finance and investment app designed to help users manage financial products, review account information, monitor savings or investment progress, and access related services from a mobile device. Its exact tools can vary by country and account type, so availability may depend on whether you are an eligible customer and which Principal products you already use.
02Is Principal® free to download and use?
The Principal® app is generally available to download at no cost from the official Android or iOS store. However, downloading the application does not mean that every financial service is free. Investment expenses, plan fees, transaction costs, or other charges may apply depending on your account and the product you use. Always review the applicable fee information before making decisions.
03Can I use Principal® without having a Principal account?
You may be able to install the app and explore its sign-in or registration options without an existing account, but many of its main features require an eligible Principal relationship. Access can depend on your country, employer-sponsored plan, retirement account, insurance product, or other service. If you cannot register, check the official eligibility requirements or contact Principal support.
04How secure is the Principal® app?
Principal® uses standard security measures intended to protect account access and personal financial information, such as encrypted connections, authentication controls, and optional device-based security features where supported. Nevertheless, no online service is completely risk-free. Use the latest app version, avoid public Wi-Fi for sensitive actions, enable biometric login when appropriate, and never share your password or verification codes.
05What should I do if I cannot log in or notice an unfamiliar transaction?
If you cannot access Principal®, first confirm your internet connection, update the app, and use the official password-recovery process rather than entering credentials repeatedly. For a suspicious login, unfamiliar transaction, or unexpected account change, contact Principal through verified support channels immediately. Do not rely on phone numbers or links received in unsolicited messages, as these may be phishing attempts.


